The Call No Property Owner Wants
A few months ago, I heard a story that stayed with me. I've changed the details here, both to make the lessons clearer and to protect the privacy of the people involved. But the heart of it is real, and it's more common than most property owners would like to think.
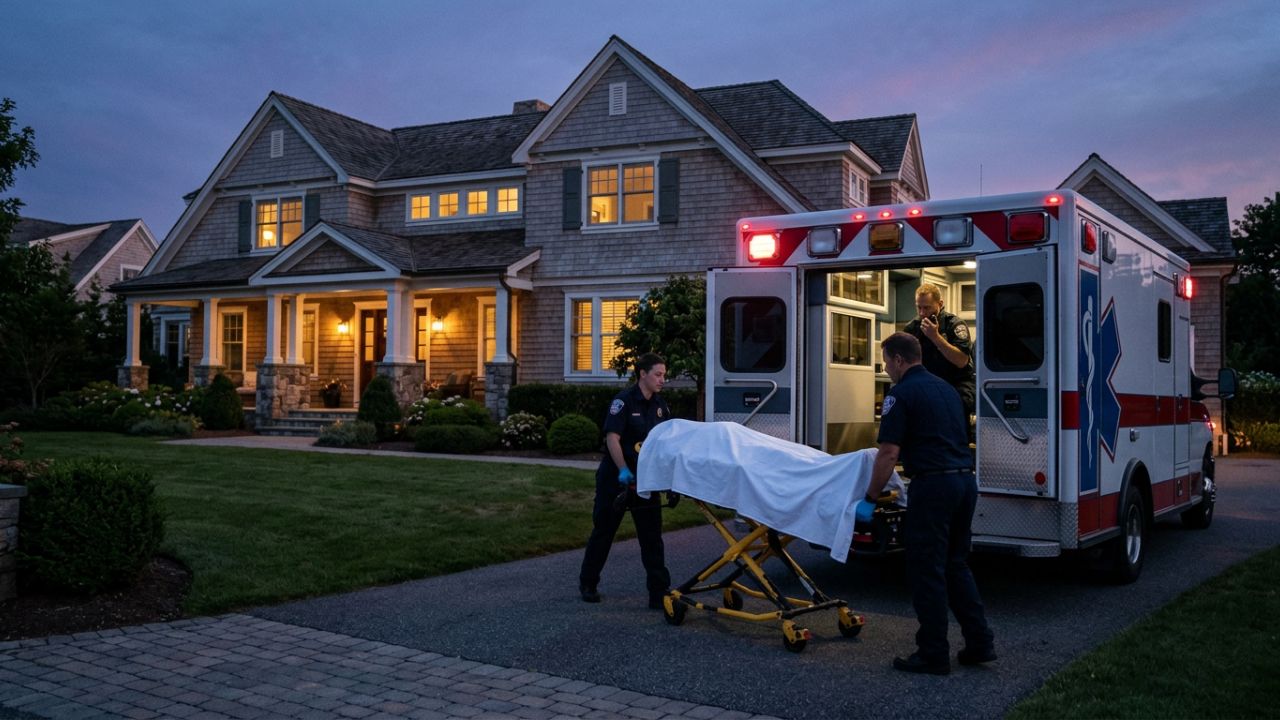
A man in his late thirties booked a week at a private vacation rental. He rented directly from the owners, a couple who had bought the property as an investment a few years earlier and held it in an LLC, as many investors are advised to do. On his third night, he was found unresponsive in the bedroom. Paramedics couldn't revive him.
At first, no one could say why he died. He was young and, by all accounts, healthy. The initial findings were inconclusive, and the answers his family desperately wanted simply weren't there. Investigators later suspected an undiagnosed condition, but by then the questions had already taken root.
Had something in the home caused it? A gas leak? Carbon monoxide? Something in the water or the air? The owners knew their property was well maintained and that the detectors were working. But they couldn't prove that nothing in the home played a role.
Six weeks later, the owners and their LLC were served with a wrongful death lawsuit.
The family was grieving and wanted answers. Without a clear cause of death, the property itself became the focus of their suspicion. In a society where lawsuits are often the first response to loss, the owners became the target, regardless of fault.
How This Usually Plays Out
The owners had done what most investors are told to do: they put the property in an LLC. An LLC does offer more protection than holding property in your own name. But in a case like this, its limits show up quickly.
In their setup, as in most, one entity did everything. The LLC owned the property, signed the rental agreements, took the bookings, and collected the revenue. That created several problems:
The asset and the activity sat in the same place. A claim arising from the rental activity landed directly on the entity that held the property and its equity.
The owners were still close to the action. Like most small investors, they managed the rental themselves. Because they were personally involved in operations, they were named in the lawsuit personally, alongside the LLC.
The protection was easy to weaken. Owners who mix personal and business funds or skip formalities give a plaintiff grounds to ask a court to disregard the LLC altogether. Small landlords do this far more often than they realize.
Being right didn't make it cheap. With no clear cause of death, the defense meant experts, testing, and years of litigation, costing tens of thousands of dollars even though the owners had done nothing wrong.
The pressure to settle was enormous. Many owners pay to make a case go away, not because they're at fault, but because the risk and expense of fighting are too great.
Attorneys who take these cases on contingency usually look at one thing early: what can actually be collected. When the property, the revenue, and the owners themselves are all within reach, the answer is "quite a lot," and that makes the case worth pursuing.
The Same Event, Structured Differently
Now imagine the same tragedy, but with a different structure. Years before anything happened, the owners set up a system of three irrevocable trusts, each with one job:
A holding trust owns the property, and does nothing else. It signs no rental agreements and runs no operations.
A business trust enters into the rental agreements with guests and tenants, whether short-term or long-term, and receives the payments.
A management trust hires and oversees the property managers who run the day-to-day.
LLC vs. three-trust separation
In the LLC, a single claim reaches everything at once. In the trust system, it lands on the trust whose role it arose from.
Each trust carries only the risk of its own role, and the owners are no longer the operators. Here's how the story changes:
The guest's agreement is with the business trust. A claim arising from the rental activity is directed at the trust that made the agreement. That trust holds the rental income, not the property and its equity.
The owners aren't on the front line. They don't sign the agreements, take the bookings, or manage the property. A trustee and a professional management structure stand between them and the day-to-day, so there's far less basis to name them personally.
The property sits apart from the activity. Because the holding trust only owns the asset, the property's equity isn't tied up in the operational side of the business.
The trustee responds, not a panicked owner. A trustee acting in a fiduciary role handles the matter calmly and professionally. Instead of defaulting to a courtroom battle, the trustee can offer private mediation. A grieving family often wants acknowledgment and answers more than a fight, and mediation can resolve the matter privately, with dignity, and far faster than litigation.
The incentive to sue shrinks. When an attorney sees that what's within reach is limited, the math behind an aggressive lawsuit often stops making sense.
A plaintiff may still name the holding trust as the property's owner in a premises claim. But its exposure is limited to that one property, and the operational liability sits elsewhere. The tragedy is no less painful. For the owners, though, it becomes a matter to be resolved, rather than a threat to everything they've built.
What a Trust Can and Can't Do
I want to be straightforward here, because asset protection is full of overpromises. A trust is a powerful tool, but it isn't magic. Here's what you should know:
A trust doesn't prevent a lawsuit. Anyone can file a claim. What a well-structured trust does is limit what a judgment can reach, and that changes how the claim plays out.
The property inside the trust is still connected to the property's risk. If a claim arises from the rental, the rental itself may be exposed. The protection is that the risk stays contained to that property instead of spreading to everything else you own. This is why many owners hold each property separately.
Timing is everything. Moving assets into a trust after an incident, or once a claim is foreseeable, can be challenged and undone as a fraudulent transfer. Protection has to be in place before you need it.
Structure matters. An irrevocable trust only protects you if it's set up and run properly, with real separation between you and the trust's assets. A trust that exists on paper but is treated like a personal bank account won't hold up.
Insurance still has a role. Good liability coverage and a sound trust structure work together. Insurance handles the cost of a claim; the trust limits what's at stake beyond it.
This Isn't Just a Vacation Rental Problem
The same logic applies to long-term rentals. A tenant slips on an icy step, a contractor is injured during a repair, or a carbon monoxide leak occurs despite your best maintenance. Any of these can lead to a claim, and the question is the same: how much of your life is exposed when it happens?
If you own several properties, the stakes multiply. Without separation, one incident at one property can put your entire portfolio at risk. With each property held separately, a problem at one address stays at that address.
A Note for Property Managers
If you manage properties for owners, you're often the first person they call when something goes wrong, and the person they trust for advice before it does. Asking your owners a simple question, "How is this property held?", can be one of the most valuable things you do for them. Owners who are properly structured are better protected, more confident, and more likely to stay in the rental business for the long haul. That's good for them, and good for your relationship with them.
Plan for the Unthinkable Before It Happens
No one buys a rental property expecting a tragedy. But owning property means accepting a certain amount of risk, and the owners who fare best are the ones who prepared before anything went wrong.
The difference between the two versions of this story isn't luck. It's structure, put in place calmly and deliberately, years before it was needed.
If you own rental property, or manage it for others, now is the time to look at how it's held:
Take the Trust Readiness Scorecard to see how relevant a private trust system is to your situation.
Join our free Trust Establishment Masterclass to learn how a robust, operational trust system is built.
Book a discovery call to talk through your properties and goals with our team.
This article is for educational purposes only and does not constitute legal, tax, or financial advice.